What is the market overview and scope of the Refined Petroleum Products Market?
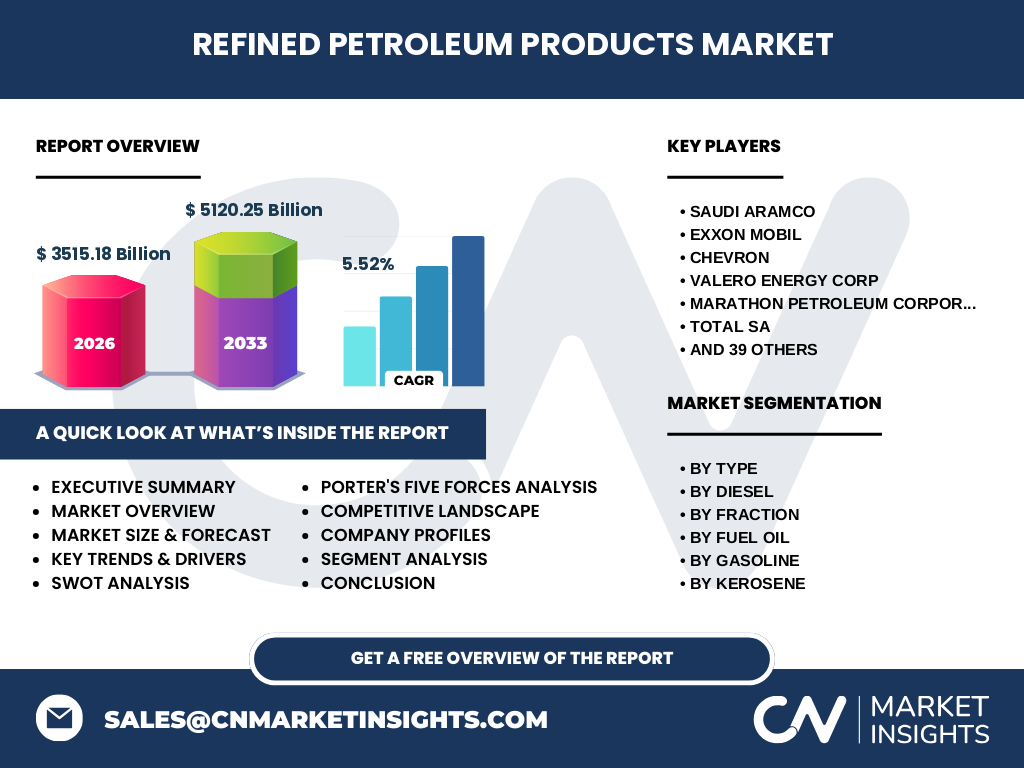
Our analysis indicates that the Refined Petroleum Products Market encompasses the conversion of crude oil into high-value commodities like diesel, gasoline, and jet fuel. Valued at 3515.18 Billion in 2026, this sector forms the backbone of global industrial mobility, chemical manufacturing, and power generation, driven by major processing hubs managed by key players like Saudi Arabia's state enterprise and Exxon Mobil.
What are the primary drivers and restraints shaping the Refined Petroleum Products Market?
The market is propelled by surging global mobility and petrochemical feedstock demand, tempered by stringent environmental regulations from bodies like the EPA and IMO. Logistics bottlenecks at key maritime chokepoints like the Strait of Hormuz create regional supply volatility, forcing refiners such as Valero Energy Corp and Marathon Petroleum Corporation to constantly optimize their catalytic cracking yields and sulfur-reduction capabilities.
What are the emerging trends and growth patterns in the Refined Petroleum Products Market?
The sector is witnessing a decisive pivot toward ultra-low sulfur diesel, hydrocracked jet fuel, and petrochemical integration. Refiners are increasingly investing in co-processing bio-feedstocks alongside traditional crude fractions. This strategic shift favors integrated operators like Total SA and Royal Dutch Shell who can balance legacy refining margins with evolving lower-carbon compliance mandates across global distribution networks.
How did the COVID-19 pandemic impact the Refined Petroleum Products Market recovery trajectory?
The pandemic triggered an unprecedented demand collapse in 2020, particularly for jet fuel and gasoline, forcing widespread refinery run-cuts and permanent facility closures in North America and Europe. Recovery has been uneven, anchored by robust post-lockdown rebounds in automotive diesel and chemical feedstocks, allowing resilient operators like Chevron and BP Plc to repair balance sheets through strict capacity rationalization.
What defines the competitive landscape and strategic dynamics of the Refined Petroleum Products Market?
Market concentration is characterized by a mix of national oil companies and supermajors wielding massive capital expenditure power. State-backed giants like China National Petroleum Corporation and Saudi Aramco dominate primary distillation capacity, while private independents like Phillips 66 and Valero compete through operational excellence, logistical integration, and complex refining configurations that process heavy, sour crude grades efficiently.
Executive Summary of the Refined Petroleum Products Market
Our comprehensive research confirms the Refined Petroleum Products Market stands at a critical juncture of traditional fuel demand and petrochemical diversification. Driven by resilient transportation and industrial needs, the market size of 3515.18 Billion in 2026 is projected to expand significantly, necessitating strategic agility from every active industry participant across the global supply chain.
Market forecast and projected growth from 2027 to 2033
The data suggests sustained expansion, forecasting the market to reach 5120.25 Billion by 2033. Achieving a steady CAGR of 5.52% from 2027 onward, this trajectory is underpinned by rising middle-class mobility in developing economies and robust demand for middle distillates, challenging refiners to expand conversion capacities while navigating tightening carbon pricing schemes.
Segmentation analysis across types, fractions, and applications
The market divides into light distillates like gasoline and naphtha, middle distillates including automotive and marine diesel plus jet fuel, and heavy oils such as fuel oil and asphalt. Applications span across fuel, chemical feedstocks, and industrial uses. Each fraction plays a vital economic role, with petrochemical feedstocks driving high-margin growth for integrated operators globally.
Regional market analysis and geographic distribution performance
Geographically, the market exhibits stark contrasts between maturing OECD economies focusing on product specification upgrades and high-growth developing regions expanding baseline refining throughput. Asia-Pacific leads consumption growth driven by rapid industrialization, while Middle Eastern producers leverage feedstock proximity to dominate export markets bound for European and North American ports.
In-depth regional review of key consuming and producing territories
Asia-Pacific remains the undisputed demand engine, anchored by massive refining complexes in China and India managed by Sinopec and Indian Oil Corporation Limited. Meanwhile, North American refiners focus on export-oriented processing of light tight oil, and European operators grapple with strict EU ETS mandates, forcing strategic capital allocation toward green hydrogen and renewable diesel integration.
Company profiles and strategic positioning of leading industry players
Industry leaders combine upstream asset ownership with complex downstream conversion capabilities. Enterprises like Saudi Aramco, Exxon Mobil, and Sinopec leverage massive scale and proprietary hydroprocessing technologies to maximize middle distillate yields. Meanwhile, specialized players focus on regional distribution networks, lubricant blending, and high-purity petrochemical precursors to insulate margins against crude price volatility.
Porter's Five Forces analysis of the Refined Petroleum Products Market
The industry experiences high capital barriers to entry and intense rivalry among established national and multinational refiners. Buyer power is moderate due to standardized commodity specifications, while supplier power fluctuates based on crude availability from OPEC+ nations. Threat of substitution remains low in heavy-duty transport and aviation, safeguarding long-term baseline demand for refined fractions.
SWOT analysis highlighting internal capabilities and external pressures
Strengths lie in established global distribution logistics and high operational complexity. Weaknesses include high capital depreciation and exposure to cyclical margins. Opportunities abound in petrochemical integration and biofuel co-processing. Threats stem from aggressive regulatory decarbonization targets, geopolitical supply disruptions, and accelerating electric vehicle adoption in passenger car segments.
Value chain analysis from crude extraction to end-user delivery
The value chain initiates with upstream extraction of crude oil, followed by maritime and pipeline transportation to coastal or inland conversion facilities. Refineries utilize fractional distillation, catalytic cracking, and hydrotreating to yield finished products. Downstream logistics via trucks, barges, and retail networks ensure final delivery to commercial, industrial, and retail end-users.
Investment insights and high-potential areas for strategic allocation
High-potential investment avenues center on upgrading complex refinery units to maximize petrochemical yield and middle distillate output. Investors should prioritize assets equipped with desulfurization and carbon capture technologies. Companies capable of seamlessly blending bio-feedstocks while maintaining high throughput efficiency present the most attractive risk-adjusted return profiles through 2033.
Conclusion and key takeaways for market stakeholders
The Refined Petroleum Products Market demonstrates enduring structural resilience, expanding toward 5120.25 Billion by 2033. Success in this capital-intensive sector requires balancing traditional fuel production with strategic pivots toward petrochemicals and low-carbon processing, rewarding agile operators who proactively adapt to shifting regulatory and consumer landscapes.
Research methodology used for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with refinery executives, and secondary macroeconomic indicators. We cross-reference throughput reports from energy agencies with financial disclosures of major market participants to ensure econometric accuracy and reliable market sizing across all defined segments.
Scope of the report, coverage parameters, and analytical limitations
This report covers global consumption, production, and trade flows of refined petroleum products categorized by type, fraction, and application from 2026 to 2033. Limitations include potential unforeseen geopolitical shocks and sudden shifts in national energy policies that could alter baseline macroeconomic projections and localized product pricing dynamics.
Recent developments, strategic partnerships, and product launches
Recent industry activity highlights aggressive investments in co-processing units and hydrogen integration. Major players like Reliance Petroleum Ltd, Total SA, and BP Plc have forged joint ventures for low-carbon fuel production and advanced chemical recycling. These strategic moves reflect a proactive industry response to tightening environmental compliance and evolving global energy demands.